

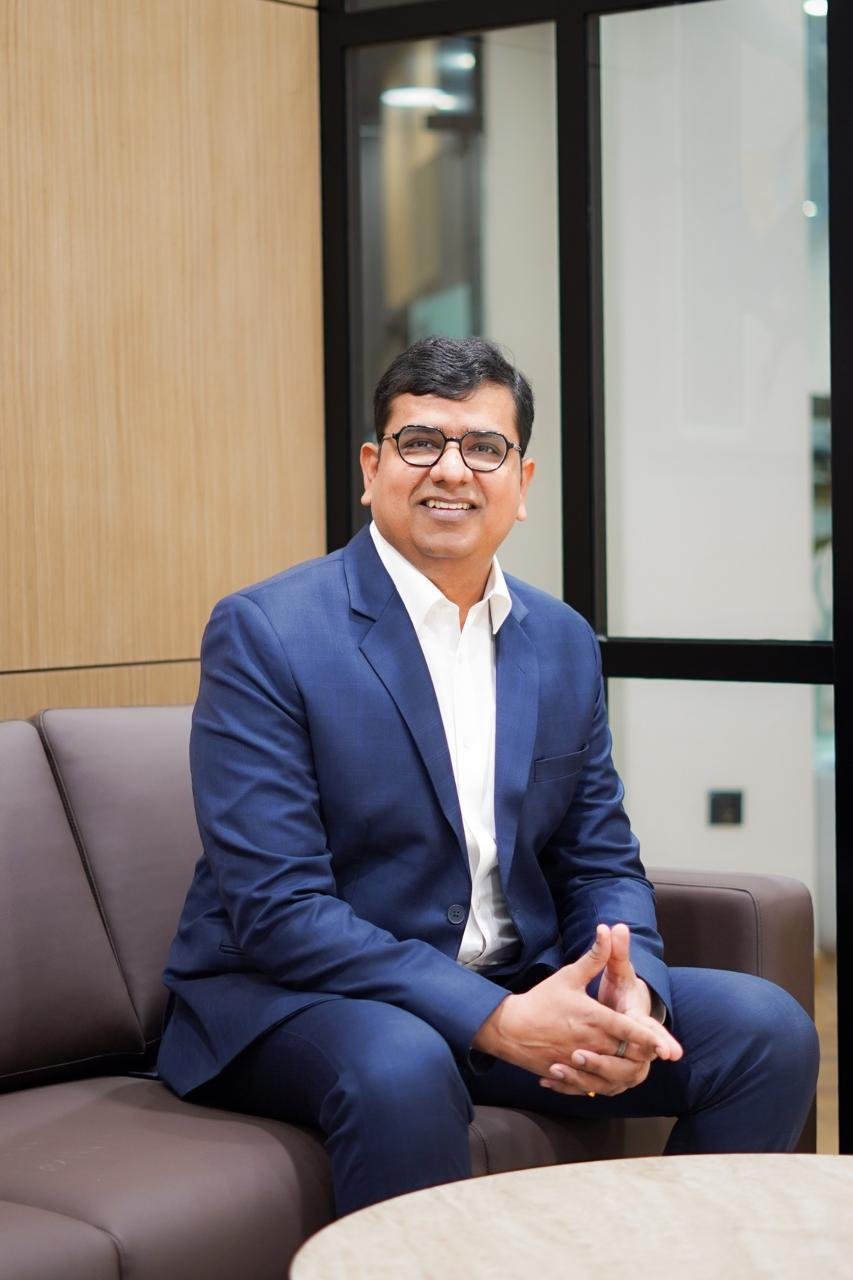
Nisus Finance sees private credit playing an increasingly important role across real estate, technology, SMEs, education, healthcare, logistics and other growth sectors, as the GCC and Egypt market is projected to grow 15–30 percent annually
Dubai,: Private credit is emerging as an increasingly important source of financing across the GCC, as businesses and asset owners seek more flexible capital structures and the region faces a financing gap estimated at more than AED 918 billion (US$250 billion). While real estate remains an important area of deployment, opportunities are expanding across sectors including technology, SME lending, education, healthcare, logistics and supply chain, as businesses seek alternative sources of growth and expansion capital.
The GCC and Egypt private credit market is projected to grow by approximately 15–30 percent annually, potentially reaching between AED 40.4 billion and AED 73.5 billion (US$11 billion–US$20 billion) by the end of the decade, highlighting the growing role of alternative financing across the region.
This momentum comes as the UAE real estate market continues to expand and developers increasingly require financing solutions beyond traditional bank lending, particularly for acquisitions, bridge financing, project completion and recapitalisation.
Dubai’s property sector delivered a record performance in 2025, with real estate investment exceeding AED 680 billion (US$185.2 billion) across more than 258,000 deals, demonstrating the significant scale of capital flowing into the sector and the growing need for diversified financing solutions.
Amit Jhunjhunwala, Chief Investment Officer, UAE, Nisus Finance, said private credit should be viewed as complementary to traditional banking rather than as a replacement. “Private credit is not replacing banks. It is completing a capital structure that has traditionally had a gap between what a deposit-taking institution can prudently lend against and what a business or asset actually requires to grow, develop or complete a transaction,” said Jhunjhunwala.
He added that this financing need is structural rather than cyclical. Prudential requirements naturally limit the types of financing banks can provide, creating a long-term role for private credit alongside traditional lenders. This can be particularly relevant for growing SMEs and businesses in sectors where financing requirements may not always fit conventional lending structures or timelines.
Private credit provides financing through non-bank institutions, with lending typically negotiated privately and structured around the specific risk profile, asset and requirements of a transaction. According to Jhunjhunwala, developers are increasingly looking to private credit not simply because of pricing, but for three critical advantages: certainty of execution, flexibility across the capital structure and the ability to underwrite the underlying business, asset or transaction rather than relying primarily on the borrower’s balance sheet.
The UAE is particularly well placed to participate in the next phase of private credit growth, supported by established financial centres including the Dubai International Financial Centre (DIFC) and Abu Dhabi Global Market (ADGM). Their regulatory frameworks, established fund structures and enforcement mechanisms have helped create an environment in which international institutional capital can evaluate and underwrite UAE opportunities.
The development of Abu Dhabi as a regional private credit centre is also strengthening the sector. Mubadala’s private credit portfolio had reached approximately AED 73.5 billion (US$20 billion) by early 2025, according to figures cited in the analysis.
Despite this momentum, private credit remains relatively early in its development across the region. As recently as 2021, private credit represented around 3 percent of total real estate debt across the UAE and Saudi Arabia, highlighting the significant headroom for the asset class to develop.
Nisus Finance sees India as an important leading indicator for the Gulf, having already experienced the transition from bank-dominated lending towards a more diversified financing ecosystem in which private credit operates alongside traditional lenders.
Private credit deployment in India reached an estimated AED 45.5 billion (US$12.4 billion) in CY2025, with real estate accounting for close to 40 percent of transactions. India’s experience demonstrates how private credit can develop alongside, rather than in place of, conventional bank financing by addressing financing requirements that traditional lenders may be structurally unable to serve.
Over the next three to five years, private credit activity in the region is expected to broaden across several areas of the economy. In real estate, opportunities are expected around residential completion and last-mile financing, acquisition and bridge financing, and recapitalisation. Beyond property, technology and growth-stage businesses, SME lending, education and healthcare, logistics and supply chain are also expected to create opportunities for flexible and structured capital.
Capital-intensive sectors including data centres and digital infrastructure, logistics and warehousing, healthcare infrastructure and hospitality could also become increasingly important areas for structured lending as investment and expansion continue across the region. Jhunjhunwala added that the growing investment relationship between India and the GCC could create further opportunities for cross-border private credit.
“India and the GCC are developing an increasingly important capital corridor. Gulf capital has duration, while Indian businesses and assets require duration capital. Private credit has the potential to become an efficient instrument connecting these two markets,” he said.
As the asset class expands, Nisus Finance believes disciplined underwriting, appropriate security structures and clearly defined exit strategies will be critical to sustainable growth.
For developers, this means evaluating the complete cost of financing, including fees, covenants, security and exit provisions. For investors, greater emphasis should be placed on realised exits, historical loss experience, position within the capital structure and the underlying security supporting an investment.
Nisus Finance operates across India and the UAE, combining its experience in India’s structured real estate credit market with a DIFC-regulated platform in the UAE. This allows the company to apply experience from a more developed private credit market to a GCC market that is still at an early stage of institutional growth.
According to the company, its funds in India have delivered approximately 20 percent average Internal Rate of Return (IRR) across realised exits, with no loss of capital across more than 15 investments.
“The GCC has the demand, regulatory architecture and capital required for private credit to develop into a meaningful institutional asset class. The opportunity extends well beyond any single sector as businesses across the region look for more flexible sources of capital. The next phase will be determined by the quality of underwriting and the discipline with which that capital is deployed,” Jhunjhunwala concluded.